UN Global Compact Leaders Summit: Turning Sustainability Ambition into Action
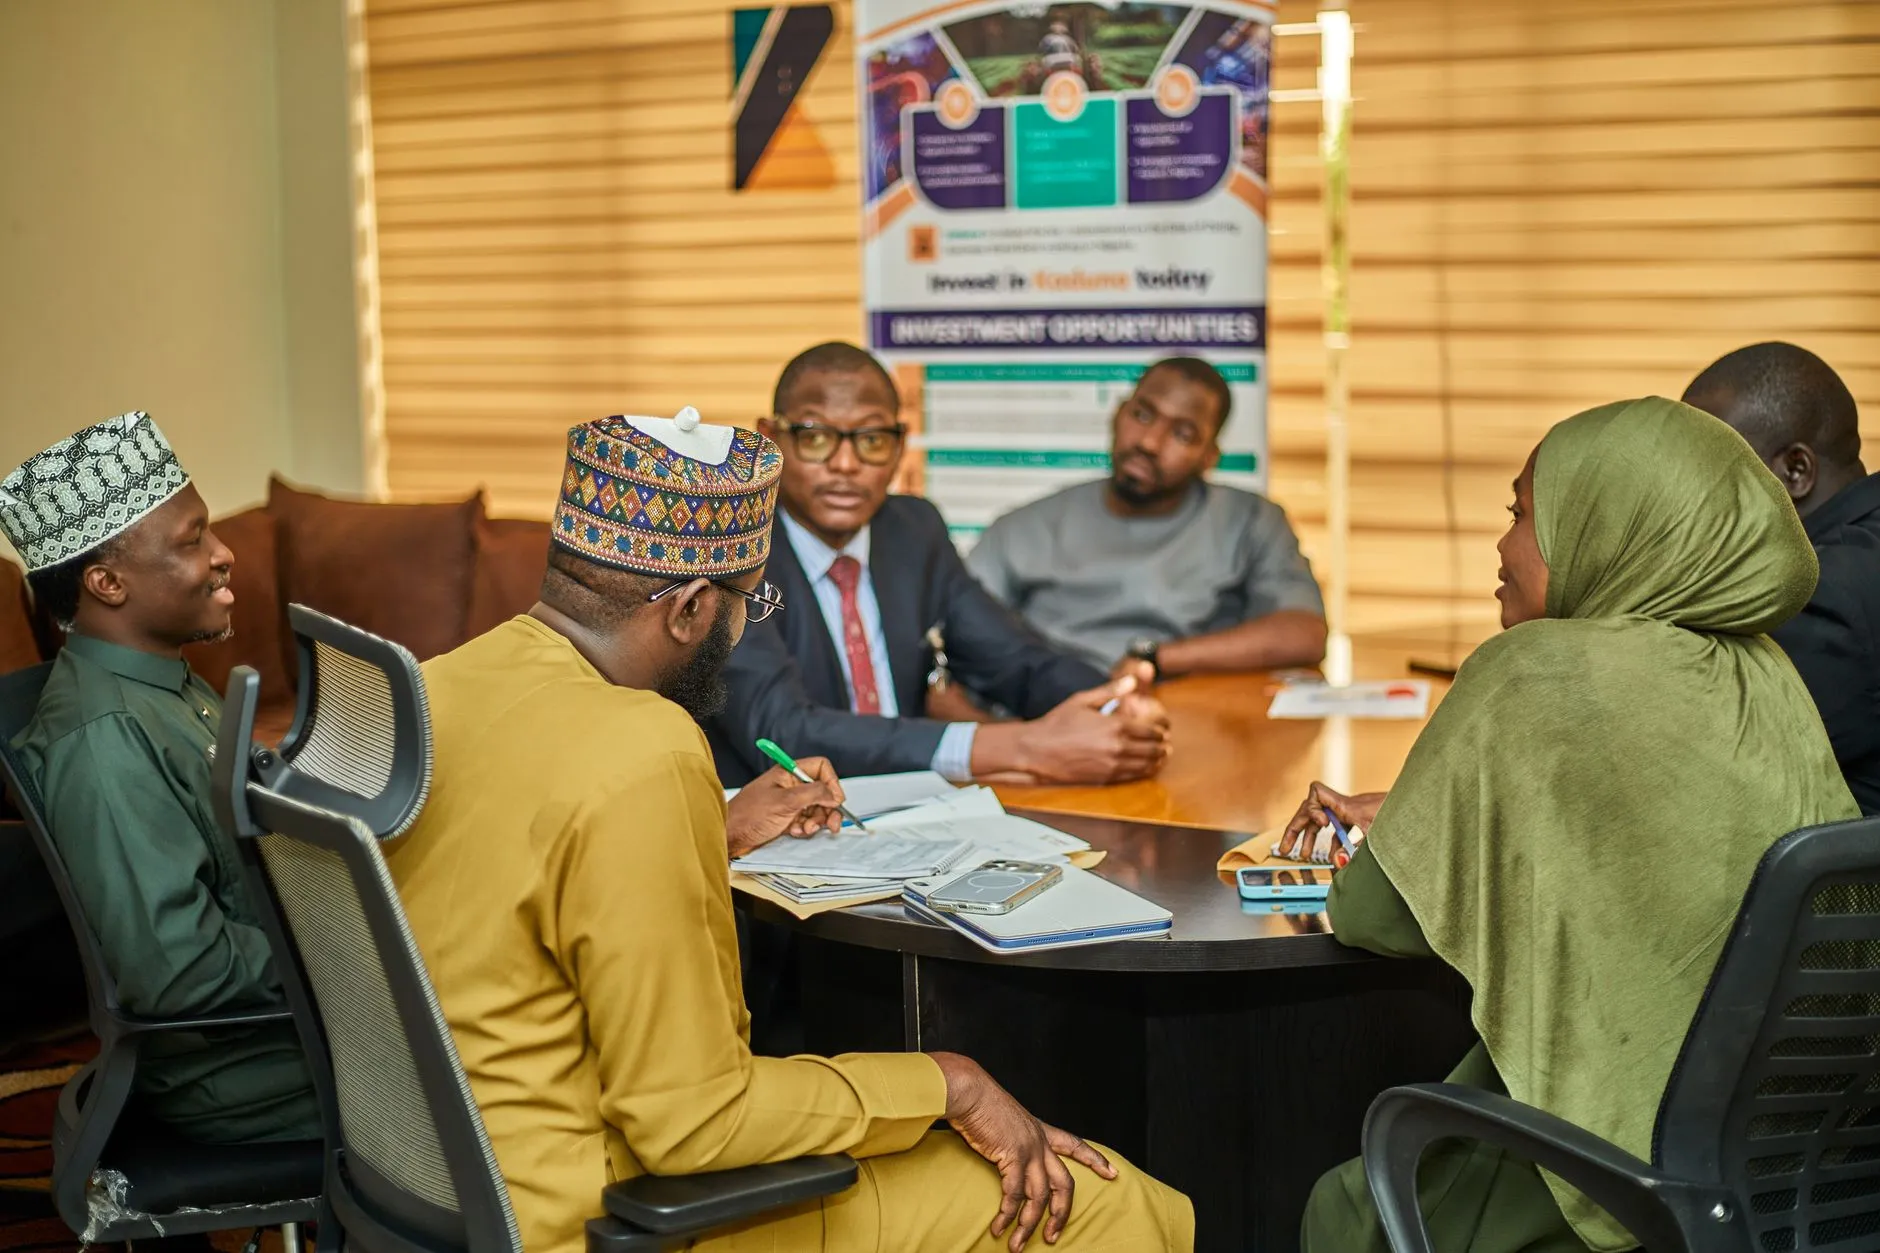
The UN Global Compact held its 2026 Leaders Summit in New York on 22 and 23 September. The event brought together more than 750 business leaders, investors, policymakers, UN representatives and sustainability professionals. The stated purpose was straightforward: push companies from making sustainability commitments to delivering measurable outcomes.
For UK SMEs operating in international supply chains or tendering for contracts with sustainability requirements, this shift matters. The summit marks a visible pivot from aspirational pledges to operational delivery. Consequently, the expectations placed on businesses at every tier are changing.
The gathering took place during UN General Assembly week. It focused on six core areas: leadership and integrity, climate and nature, human rights and decent work, sustainable finance and capital, collective action and systems change, and policy, procurement and supply chains. Each of these areas has direct commercial implications for businesses supplying into multinational value chains or competing for public sector work in the UK.
Understanding what happened at this summit helps businesses anticipate how sustainability expectations will evolve. It also clarifies where attention is shifting across global corporate networks, which in turn affects procurement standards, tender criteria and investor due diligence.
What the UN Global Compact is doing differently
The UN Global Compact runs an annual flagship event during UN General Assembly week. This year's summit was held at the New York Marriott Marquis. The initiative works to align company strategies with Ten Principles covering human rights, labour standards, environmental responsibility and anti-corruption. It also encourages progress toward the Sustainable Development Goals.
The 2026 event reflects the organisation's updated 2026 to 2030 strategy. This strategy emphasises three shifts. First, a tailored digital learning journey for participating companies. Second, collective action across climate and nature, decent work and living wages, gender equality and sustainable finance. Third, a stronger evidence base using platforms such as Forward Faster and the CFO Coalition for the SDGs.
The summit was designed around practical frameworks and partnership guidance. Sessions aimed to equip leaders with the tools needed to move from ambition to results. This framing suggests the UN Global Compact is addressing a widely recognised problem: many companies have set targets but lack the systems to deliver them.
The event took place against a backdrop of geopolitical uncertainty, economic volatility and rapid technological change. Pressure is mounting on companies to show tangible progress. Therefore, the summit focused on building systems for long-term sustainable growth and mobilising business at the scale required to deliver meaningful outcomes for people and the planet.
Six priority areas for corporate sustainability delivery
The summit was organised around six issue tracks. Each track addresses a different dimension of corporate sustainability performance. Together, they cover most of the material risks and opportunities facing businesses with environmental, social and governance responsibilities.
Leadership and integrity was the first track. This area centres on governance, transparency and accountability. It reflects growing expectations that boards and senior management take direct responsibility for sustainability performance, not just endorse it in principle.
Climate and nature formed the second track. This covers emissions reduction, energy transition, biodiversity and natural capital. For UK manufacturers and service providers, this track links directly to carbon reporting requirements, Scope 3 emissions in supply chains and emerging nature-related disclosure frameworks.
Human rights and decent work was the third focus area. It addresses labour standards, health and safety, fair wages and working conditions. Businesses exporting goods or sourcing materials internationally face increasing scrutiny on these issues, particularly where supply chains involve high-risk regions or sectors.
Sustainable finance and capital was the fourth track. This area deals with how investment decisions, capital allocation and financial reporting integrate environmental and social factors. Investor expectations are shifting rapidly. Consequently, companies that cannot demonstrate credible sustainability performance may face higher costs of capital or reduced access to funding.
Collective action and systems change formed the fifth track. This recognises that many sustainability challenges cannot be solved by individual companies acting alone. Instead, progress depends on collaboration across industries, geographies and value chains. Examples include shared infrastructure for renewable energy, industry-wide standards for waste reduction or coordinated efforts to improve labour conditions in specific supply chains.
Policy, procurement and supply chains was the sixth and final track. This area addresses how government policy, public procurement rules and supply chain requirements drive corporate sustainability performance. For UK SMEs, this track is particularly relevant because it shapes tender criteria, supplier qualification standards and contractual obligations.
How this affects UK businesses in practice
The summit signals a broader shift in how sustainability is understood and managed. Previously, many companies treated sustainability as a separate initiative, often managed by dedicated teams with limited integration into core operations. That approach is changing. Sustainability is now increasingly tied to competitiveness, risk management and market stability.
For SMEs, this shift has several practical implications. First, customers and procurement teams are asking more detailed questions about carbon footprints, supply chain conditions and environmental performance. These questions often form part of formal tender processes, particularly for public sector contracts or large corporate supply agreements.
Second, reporting expectations are expanding. Many businesses are now required to provide data on emissions, energy use, waste and water consumption. This data feeds into customer reports, investor disclosures and regulatory filings. Consequently, businesses without robust data collection systems may struggle to meet customer requirements or qualify for certain contracts.
Third, access to finance is increasingly linked to sustainability performance. Banks, investors and insurers are integrating environmental and social factors into lending decisions, investment criteria and underwriting standards. Businesses with poor sustainability performance or inadequate disclosure may face higher interest rates, reduced credit availability or increased insurance premiums.
Fourth, supply chain expectations are rising. Large companies are under pressure to reduce Scope 3 emissions, which are generated by their suppliers. As a result, they are setting stricter requirements for suppliers, including carbon reduction targets, renewable energy use and waste minimisation. Suppliers that cannot meet these requirements may lose contracts or face pressure to improve performance quickly.
Fifth, regulatory requirements are tightening. The UK government has introduced new rules on energy efficiency, carbon reporting and environmental disclosure. These rules affect both direct compliance costs and the information businesses must provide to customers, investors and regulators. Companies that fail to comply risk penalties, reputational damage and exclusion from certain markets.
Sixth, technological change is creating both opportunities and risks. Digital tools for carbon accounting, energy management and supply chain transparency are becoming more accessible and affordable. However, businesses that do not adopt these tools may find themselves at a competitive disadvantage compared to peers that can provide better data and demonstrate stronger performance.
Core facts from the 2026 summit
- More than 750 participants attended the two-day event in New York, including business leaders, investors, policymakers and UN representatives.
- The summit was structured around six issue tracks covering leadership, climate, human rights, finance, collective action and supply chains.
- The event reflects the UN Global Compact's 2026 to 2030 strategy, which aims to turn sustainability ambition into action at scale.
- The strategy prioritises tailored digital learning, collective action across key sustainability issues and a stronger evidence base through dedicated platforms.
- The summit was held during UN General Assembly week at the New York Marriott Marquis on 22 and 23 September.
- The UN Global Compact works with companies to align strategies with Ten Principles on human rights, labour, environment and anti-corruption.
- The initiative also encourages progress toward the Sustainable Development Goals through coordinated business action.
Preparing for the next phase of sustainability expectations
The message from the summit is clear: sustainability is moving from ambition to implementation. Businesses should expect more detailed questions, stricter standards and greater scrutiny of actual performance rather than published commitments.
For UK SMEs, the priority is to establish systems that can generate credible data and demonstrate measurable progress. This means setting up carbon accounting processes, tracking energy use, monitoring waste and understanding supply chain impacts. Without these systems, businesses will struggle to respond to customer requests, meet regulatory requirements or qualify for contracts with sustainability criteria.
It also means thinking about sustainability as an operational issue, not a communications exercise. Performance improvements in energy efficiency, waste reduction or supply chain management often reduce costs, improve resilience and create competitive advantages. Therefore, businesses that treat sustainability as a compliance burden may miss opportunities to strengthen their commercial position.
Collaboration is becoming more important. The summit's emphasis on collective action reflects a growing recognition that many sustainability challenges require coordinated responses. Industry groups, trade associations and regional networks can help businesses share knowledge, access resources and develop common standards. Participating in these initiatives can reduce costs, accelerate learning and improve outcomes.
Training and capability building also matter. Many businesses lack the internal expertise needed to manage sustainability effectively. Investing in staff training, accessing external support or using digital tools can help close this gap. SBS Academy training on carbon reporting and Scope 3 emissions provides practical guidance for businesses working to improve their sustainability performance.
Finally, businesses should prepare for ongoing change. Sustainability expectations will continue to evolve as regulations tighten, customer requirements increase and investor scrutiny intensifies. Building flexible systems, maintaining up-to-date knowledge and staying engaged with industry developments will help businesses adapt as standards change.
For businesses working to meet carbon reporting requirements or prepare for public sector tenders, our net-zero program for carbon reporting compliance offers structured support aligned with UK regulatory expectations.
Where to find authoritative guidance
The UN Global Compact website provides detailed information on the Ten Principles, the Sustainable Development Goals and how businesses can participate in the initiative.
The UK government's net zero strategy sets out the policy framework affecting businesses operating in the UK, including regulatory requirements and support schemes.
The Department for Energy Security and Net Zero publishes guidance on energy efficiency, carbon reporting and climate-related business requirements.
The UK legislation website provides access to all statutory instruments and regulations affecting environmental and social performance, including the Companies Act requirements for sustainability reporting.